IRIS access alone is not legal service, LHC rules
What the source reports
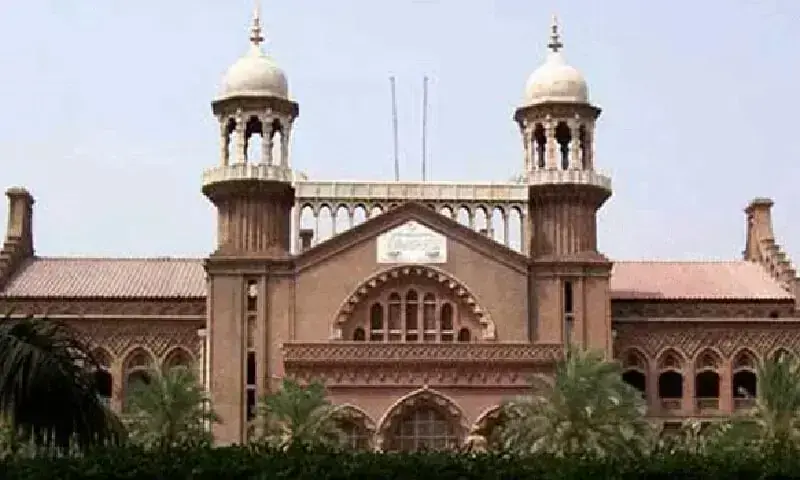
LAHORE: The Lahore High Court has held that merely uploading an appellate order to the Federal Board of Revenue’s (FBR) Inland Revenue Information System (IRIS) does not constitute valid service under the Income Tax Ordinance, 2001. An LHC division bench comprising Justice Mirza Viqas Rauf and Justice Anwaar Hussain decided three connected reference applications led by Tahir Mehmood. The applications challenged three orders of the Appellate Tribunal Inland Revenue, which had dismissed the taxpayers’ appeals as time-barred on the ground that uploading the orders to IRIS constituted sufficient service. In one case, the taxpayer argued that Covid-19 and quarantine following a foreign trip had prevented him from accessing the portal.
In the other two cases, the taxpayers said they learned of the Commissioner (Appeals)’ orders only after receiving recovery notices in April 2026, months after the orders had been passed. Justice Anwaar Hussain, who authored the judgement, held that Section 218(1)(d) of the ordinance recognises electronic service only when carried out in the prescribed manner. He observed that Rule 74 of the Income Tax Rules limits an electronic address to a fax number or an email address and requires confirmation of transmission. IRIS, by contrast, is an internal, web-based workflow system for tax administration, the judge noted, adding that placing an order in a taxpayer’s account does not establish its transmission to an electronic address as required under the rule. The judge distinguished between accessibility and service, observing that an order may be accessible without having been served in accordance with the law. He further held that the limitation period could not begin from an event that the law did not recognise as its starting point.…
TDBN presents the written preview supplied through the publisher's feed. Complete reporting, continuing updates, context, and corrections remain with the original report.
Read the complete report ↗